Karine*, 42, is a communications assistant at a small marketing agency. She lives with her partner in a condo they bought 5 years ago. Together, they share a car, live simply, and manage to put a little money aside. Her employer doesn't offer a pension plan, so Karine knows she'll have to rely on herself to build her future.
She wants to save more, but without sacrificing the little things that make life sweet: good restaurants, an annual getaway, and a thriving social life. Not to mention her dream trip to Paris. How can she balance all these priorities while saving for a comfortable future?
Financial situation
- Salary: $65,000 per year
- Savings:
- Pension plan: none
- Debt:
- $300,000 mortgage (20 years remaining)
- $23,000 car loan (5 years remaining)
Our advice
"Karine should start by getting a clear picture of her financial situation. With My Game Plan, she'll have a better idea of where she stands."
– Sébastien Lafontaine, FlexiFonds mutual fund advisor and financial planner
The tool will provide a comprehensive portrait of her finances and goals—exactly what she needs to make informed decisions and figure out how much to save.
Key information to enter into the tool
In order for My Game Plan to provide Karine with the recommendations best suited to her situation, Sébastien Lafontaine recommends that she enter the following information:
- Complete family situation: She can start by building her plan on her own, then add her spouse's data later. This will give the tool an accurate picture of her household income and expenses.
- Savings accounts: Her Fonds account is already in the tool, but she will have to add her TFSA and accounts held elsewhere.
- Assets: The condo (market value + price paid) and the couple's car. This will enable the tool to correctly calculate the household's net worth.
- Debts: Mortgage and car loan. Monthly payments are taken into account in the plan.
- Her retirement expenses: Imagining what life will be at age 65 isn't easy. My Game Plan helps. Does Karine want to spend more, about the same, or less than she does today?
Did you know?
To calculate projected retirement expenses, My Game Plan uses current net income, then deducts debt repayments and savings. The result is a fairly realistic estimate of future expenses—more accurate than the "70% of income" rule of thumb.
Strategies
Once all the information has been entered, My Game Plan will generate the completion percentage of her retirement goal. Karine scored 91%, which is a great place to start! But she needs to do a little more to reach 100%, and her travel goal needs to be integrated into her plan. My Game Plan suggests several strategies for improving her situation.
01Increase RRSP savings
When she retires, Karine will be able to count on government benefits to provide a base income. Her savings will have to make up the rest.
My Game Plan recommends that she contribute an extra $350 a month into her RRSP. If this isn't possible right now, Karine can choose another amount. The important thing is getting closer to her goal.
"The trick is to put money aside as soon as your paycheque comes in," says Sébastien Lafontaine. "You can set up payroll deductions or automatic withdrawals. What you save today will help you accumulate substantial funds later on."
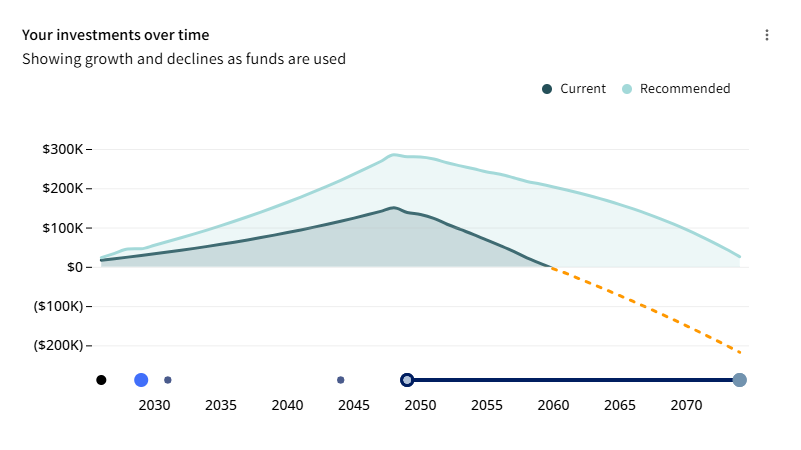
To see what this might look like, Karine can check out the Your investments over time graph to the right of the recommendation. Putting an extra $350 a month into an RRSP would give her $142,000 more at age 65, which means she would be less likely to run out of funds in her later years.
02Save all tax refunds
This is a simple but powerful strategy when combined with the previous one. The more Karine contributes to her RRSP, the bigger her tax refund will be. Instead of treating her refunds as extra money, she could systematically use them to boost her savings. This strategy has an impressive snowball effect.
Note: Karine contributes to her RRSP+ via payroll deduction, so tax savings from the RRSP deduction are already applied to her paycheques. If she wants to save her tax refund, she will have to be disciplined and set the equivalent amount aside.
03Build an emergency fund
Karine and her partner don't have a financial cushion. If something unexpected happens, such as a job loss, a broken appliance, or car problems, she'll have to take on more debt. This could compromise her retirement savings or travel plans.
She could add an emergency fund goal in My Game Plan. Sébastien Lafontaine recommends setting aside 3 to 6 months of expenses. "You can use your tax refund to boost your emergency fund," he suggests. "The important thing is to gradually build it up."
My Game Plan tip
When you add an emergency fund goal, the tool helps you calculate how much you need to save. In the Save to replace field, select Monthly expenses. This will give you a more realistic savings amount than when the calculation is done using your monthly salary.
04Increase savings once the condo is paid off
In 20 years, Karine's mortgage will be paid in full. This will be the perfect opportunity to redirect her freed-up funds into savings.
My Game Plan recommends that Karine and her partner save the equivalent of their monthly mortgage payment ($1,907/month) once they are done paying off their mortgage, around 2044. This would give Karine 5 years of intensive savings before she retires in 2049. What's more, once her car loan is paid off in 5 years, she can put that money into savings for a few years. "Since the couple are used to living without that money," says Sébastien, "Why not keep living without it and use the funds to get richer rather than to repay a debt?"
My Game Plan tip
You will see the recommendations that you accept in your action list. This is your to-do list. Check the due date for each action to find out when you need to implement it. Some will be relevant way down the road, when you retire or even later.
05Add her travel project to the plan
Karine and her partner dream of visiting Paris in 3 years. They estimate the cost of the trip at $8,000. Adding this goal to their plan will help them to save up before they leave.
When they add a Save for a major expense goal to My Game Plan, the tool recommends that they each save $115 a month in their own TFSA for 37 months. Working to save together will help keep them motivated!
"For this type of project, the earlier you start planning, the better. This gives you time to build up your capital and enjoy a trip that lives up to your expectations," advises Sébastien Lafontaine.
Where to start
Getting all these recommendations is great, but it can be hard to figure out where to start. Check out our family budgeting article for helpful advice on how to allocate your savings in a balanced way.
Bonus: Make a budget to stay on top of spending
Sébastien Lafontaine's final piece of advice for Karine is to make a budget and track it regularly. "Budgeting helps us know how much flexibility we have to work with. Until we make one, we don't always realize what we're spending our money on."
Since she likes to go to restaurants, Karine could include this type of expense in her budget and take full advantage of it when the opportunity arises, knowing that she has money earmarked for eating out. Monthly savings should also be included in budgeted expenses.
See clearly with a solid plan
Like Karine, you can turn your questions into a clear, motivating plan. My Game Plan helps you know exactly where you stand, make informed decisions, and make progress towards the retirement you want—without sacrificing what matters to you.
Plan your savings strategy with confidence
My Game Plan will help you visualize all your assets, choose the right retirement savings strategy, and achieve other life goals. Do you save with us? Use the tool free of charge from your online account.