Recently arrived in Québec and already thinking about your future here? That's great! Taking time to understand Québec's retirement system is one of the first steps to ensuring long-term financial security.
How does retirement work in Québec? Are you entitled to pensions? What kind of income can you expect? Let's answer your questions.
How does retirement work in Québec?
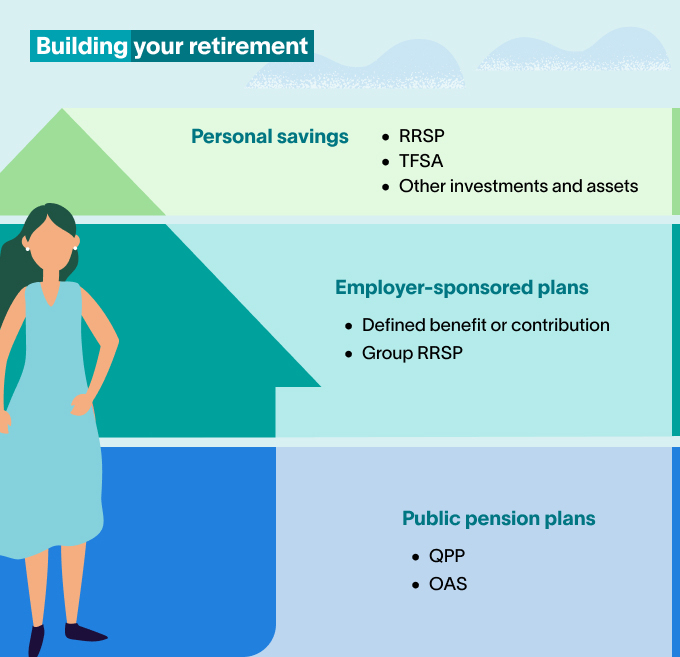
In Québec, retirement income comes from three complementary sources: public pension plans, employer-sponsored pension plans, and personal savings.
| Public pension plans |
|
|---|---|
| Employer-sponsored group retirement plans |
|
| Personal savings |
|
While public pension plans constitute a solid foundation, they are rarely enough on their own to maintain your standard of living in retirement. Employer-sponsored plans and personal savings also play an important role. Every extra dollar you set aside counts, and it's never too early to get started.
Will I be entitled to a retirement pension in Canada, even if I've just arrived? Yes. You can begin building a retirement here as soon as you start working. Let's take a closer look at each source of income.
Public pension plans
Provincial: Québec Pension Plan (QPP)
The QPP is managed by Retraite Québec. As soon as you turn 18 and earn more than $3,500 a year, you are required to contribute a portion of your salary regardless of your immigration status.
Under this plan, the retirement age is typically 65. However, you can begin to receive reduced payments as early as age 60 or postpone them until age 72 and receive higher payments. The amount you receive also depends on your income and years of contribution.
Federal: Old Age Security (OAS) pension
Paid by Service Canada from age 65, the OAS pension is calculated based on your years of legal residence in Canada after age 18 (a minimum of 10 years for a partial pension, 40 years for a full pension). You must hold Canadian citizenship or residency status at the time of application. You can also defer the OAS pension until age 70 to receive higher monthly payments.

Group retirement plans offered by your employer
Many Québec employers offer their employees private retirement savings plans to complement public pension plans. Here's what your workplace might offer:
- Supplemental pension plan (SPP), also known as a pension fund. There are two main types: defined benefit (your future pension is known in advance) and defined contribution (the amount accumulated depends on returns). If an employer offers one, both the employer and the participating employees must contribute.
- VRSP and group RRSP. These savings accounts are opened in your name and are funded by contributions deducted automatically from your pay. While not obligated, your employer may also contribute.
Whether or not your employer contributes, participating in a workplace retirement savings plan is one of the best ways to save. It's automatic, and management fees are generally lower than for individual savings plans.
Would you like to know more about what your employer offers? Ask your human resources department for more information.
Personal savings: Two important tools
In Québec, there are two main options for supplementing your retirement savings at your own pace: the TFSA and the RRSP.
TFSA: Start as soon as you arrive
A TFSA is a savings account for growing your money tax-free. Earnings and withdrawals are never taxed.
As soon as you establish Canadian tax residency and turn 18, you begin to accumulate TFSA contribution room regardless of your income. This is often the first tool to use when settling in Québec.
RRSP: Pay less tax now
RRSPs are accounts in which investments grow tax-free until retirement. Each contribution reduces your taxed income. Your contribution room is based on your earned income for the previous year. As with a TFSA, tax residency is all that's required to make contributions. Withdrawals are taxable, however, with certain exceptions (buying a first home and returning to school, for example).
Fonds shares: Maximize your tax savings
Owning shares in labour-sponsored funds may entitle you to tax credits of 30%[1] on the first $5,000 invested each year. It's a tangible advantage that helps you maximize every dollar you save. If you hold these shares in an RRSP, you may also benefit from a tax deduction. Your contributions can be deducted directly from your paycheque if your employer is registered with the Fonds. To take advantage of this option, contact your payroll department.
Learn about retirement in Québec
Here are answers to our most frequently asked questions.
At what age can I retire here?
The usual retirement age in Québec is 65. With life expectancy often exceeding 85 years, this stage of life can surpass 20 years. Prepare now to ensure sufficient income for this entire period.
Timing your pension application correctly can make a huge difference. We've done the math, and deferring payments until age 70 can mean an additional $100,000 or more in your pocket.
Do my years as a temporary worker count?
Yes, for the QPP. As soon as you start working in Québec, turn 18, and earn more than $3,500, you begin contributing to the QPP. You must then contribute for at least one year in Québec to be eligible.
To receive the OAS pension, you must hold Canadian citizenship or residency status at the time of application and have resided in Canada for a minimum of 10 years after the age of 18.
Can I combine my home country's pension with Canadian pensions?
Yes, in many cases. Québec has social security agreements with 39 countries. These agreements allow you to combine your years of work in both countries to reach eligibility thresholds. They don't increase the amount of your pension but can help you access it sooner. Visit the Retraite Québec and Government of Canada websites to find out if your country of origin is included.
What if I go back to my home country?
Good news: In many cases, you'll be able to benefit from retirement savings accumulated in Canada. Entitlements vary, however, depending on your situation, type of savings, how long you've been in Canada, and social security agreements between Canada and your country of origin. For example, funds accumulated in an RRSP with the Fonds de solidarité FTQ can be withdrawn if you leave Canada permanently. Other conditions apply.
We recommend consulting an advisor before leaving Canada to avoid unpleasant tax surprises.
Every action counts
Building your retirement in Québec means making the most of three complementary sources of income: public pension plans, employer-sponsored plans, and personal savings. The sooner you get them working together, the more flexibility you'll have when it comes to enjoying your retirement.
Map out a clear path to retirement
Try the My Game Plan tool to map out your finances! It's simple and intuitive to use, and it helps you visualize all your savings, test different scenarios, and get personalized recommendations to reach your goals.